Summary: Anthropic now has two lab-backed delivery arms in Ode and its new European venture with Hg, and the consensus is that they hit implementation work at Accenture and the Big Four hardest. The strategy house looks safe on revenue, but it is exposed on AI talent, and that is the harder thing to win back.
- Lab-backed consultancies such as Anthropic’s venture with Hg follow the Palantir model of forward-deployed engineers paid on what gets built, with private equity as the sales channel.
- Integrators such as Accenture and the Big Four lose implementation revenue first, but strategy consulting firms lose senior AI talent first.
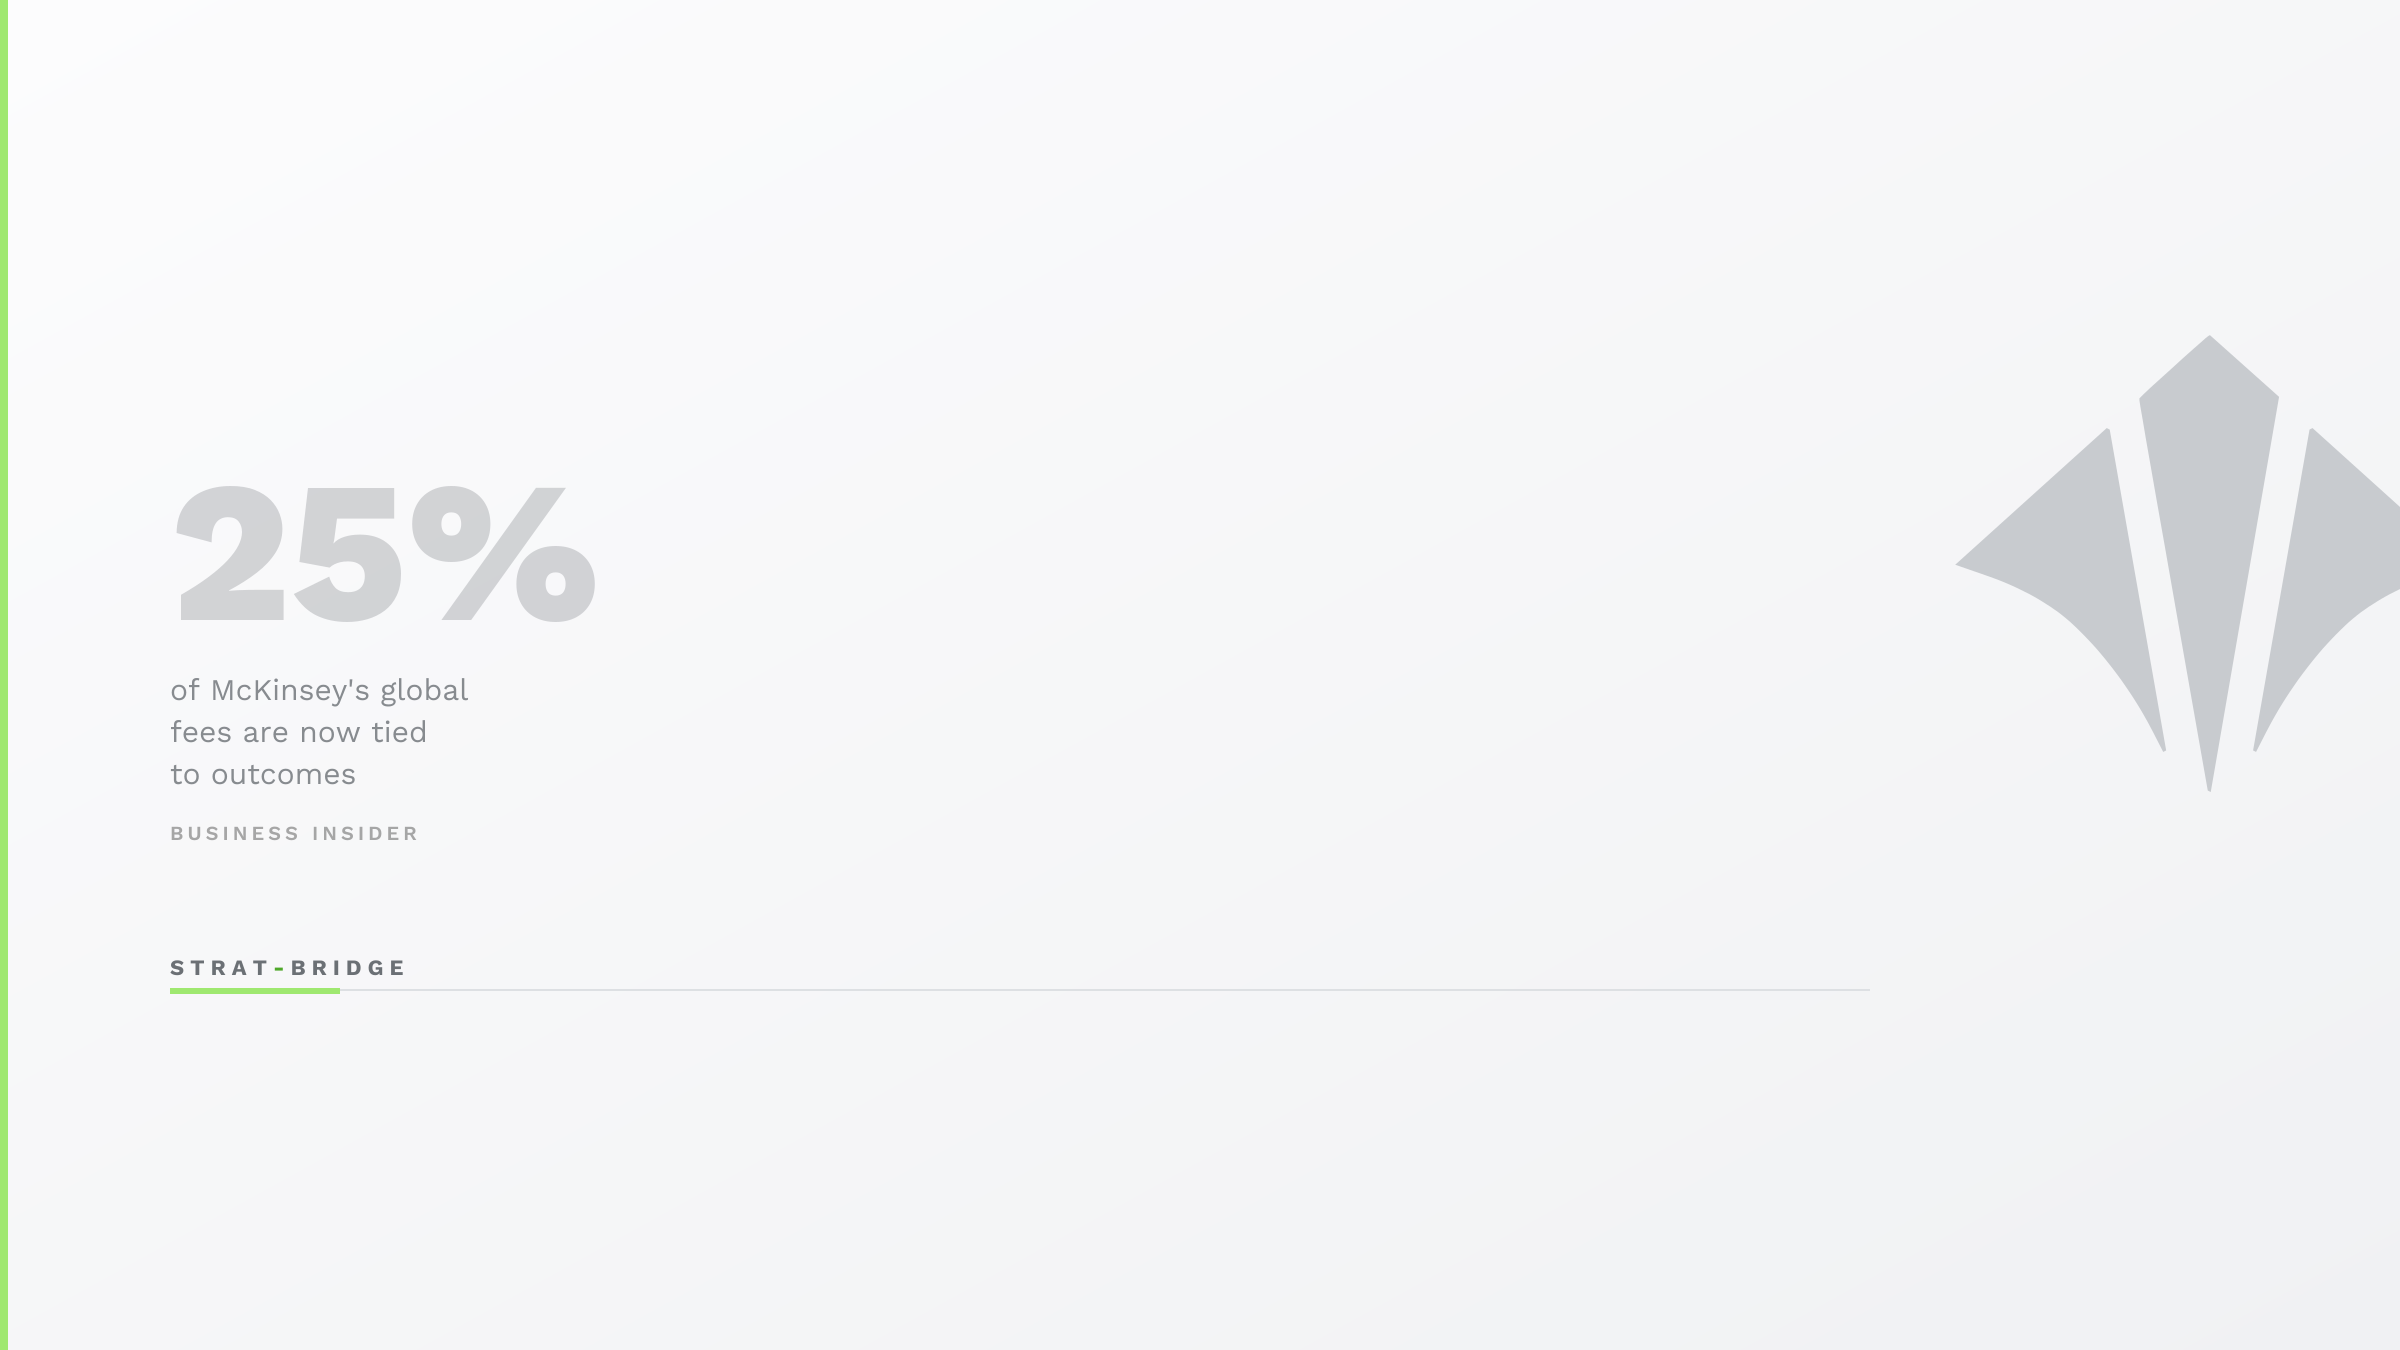
- About a quarter of McKinsey’s global fees already come from outcome-based pricing, according to its UK managing partner Michael Birshan.
- The senior data and AI leaders who can advise a board and bridge into operations are now the most contested hire in European consulting.
Strategy firms could win the argument about AI and still lose their best people to it.
Last week I wrote that the Anthropic consultancy runs through PE. Anthropic and Hg are setting up an independent consultancy to embed AI engineers inside European businesses, with hubs in London and Berlin and a launch planned by the end of 2026, as first reported by the Financial Times.
I closed that post with a question. Who loses most from the lab-backed consultancies, the integrator or the strategy house?
Forbes has had a go at answering it. In five ways consulting has to change, Alexander Puutio argues firms must stop selling research, put engineers inside the client, work across every model, make the client’s own knowledge usable by machines, and get paid on outcomes.
Four of those five are integrator problems, which on paper means the strategy house gets off lightly.
To be honest, I don’t buy all of it.
The integrator loses revenue first. The strategy house loses talent first, and talent is harder to get back.
Lab-backed consultancies run the Palantir playbook with a PE sponsor
Anthropic’s venture with Hg looks like the Palantir model with a private equity fund as the distribution channel. Forward-deployed engineers sit inside the client and get paid on what gets built, not on hours billed.
Palantir is the proof the model pays. Forbes reports that Palantir’s US commercial revenue reached $764 million in the second quarter of 2026, up 149% on the year before, on the back of exactly this embedded approach.
Anthropic has been building towards this all year. In February I asked who would become Anthropic’s preferred transformation partner, after OpenAI chose its consulting corner with McKinsey, BCG, Accenture and Capgemini. The answer, it turns out, is Anthropic itself.
First came Ode, the $1.5 billion services firm Anthropic launched with Blackstone and other investors, which I argued was a fifth consulting model. Now comes Hg for Europe, where the sponsor signs and the portfolio company implements.
If that is the model, it does not stop at implementation. Once an engineer is inside the client and paid on outcomes, the next conversation is about what should be built, which is strategy work.
Four of Forbes’s five changes are integrator problems
Alexander Puutio’s five changes in Forbes mostly describe work that Accenture and the Big Four do today. Embedding engineers, connecting systems and structuring client data are integrator territory.
The Financial Times named Accenture and the Big Four as the firms most exposed to the Anthropic and Hg venture. Advising on technology adoption is already a major revenue line for them.
The twist is that Anthropic is already inside those same firms. Accenture formed a dedicated Anthropic business group and is training around 30,000 people on Claude, and Deloitte has rolled Claude out across its workforce. Anthropic is now partner and competitor to its own biggest channel.
The fifth change, getting paid on outcomes, is the one that reaches strategy firms. About a quarter of McKinsey’s global fees already come from outcome-based pricing, Michael Birshan, McKinsey’s UK managing partner, told Business Insider.
Pricing pressure reaches the strategy day rate next
Clients are already asking integrators for the AI version of a service at a fraction of the old cost. On my calls this year, people inside managed-service providers describe clients turning up to renewals asking to swap FTEs for AI at a tenth of the price.
That conversation reaches the strategy day rate next, maybe not this year, but it is coming.
I have written before that the signal to watch is how firms get paid, not what they say about AI. A partner billing five to eight thousand a day has to explain what a client gets that a forward-deployed team paid on results does not.
The honest answer is judgment, access and the ability to get something through a board. That answer only holds if the firm has the people to back it up.
Clients and labs are bidding for the same AI talent
The senior data and AI leaders who can bridge strategy and operations are the most contested hire in European consulting right now. In the market I see, tech-side packages for these people run at €600-800k and above.
Some of them are getting offers from their own clients. That used to be rare at associate partner level. This autumn I have heard it more than once.
The strategy house wants that person advising the board and keeping the partner day rate intact. It explicitly does not want them running a 12-month implementation.
The lab-backed firm wants them building, and it can pay in equity. Same person, two very different jobs.
That is a hard trade for an incumbent to win on cash alone. If this is you, it is worth joining our leadership network before you decide.
The strategy house wants them advising the board. The lab-backed firm wants them building, and pays in equity.Ben Appleton, Strat-Bridge
The AI talent brief has changed in a year
Strategy consulting firms now brief for AI roles that did not exist twelve months ago. One firm’s internal AI brief I have seen reads agent harness, MCP, EU AI Act, token cost control and agent governance.
The same brief noted that the preferred model inside the firm had moved from ChatGPT to Claude, and might move again. The person in the seat has to stay ahead of that change, not react to it.
That profile is roughly 40% technical and 60% managerial. It is very hard to find, because most candidates are either strong on adoption and change, or strong on engineering, rather than both.
The firms moving fastest already have around one in ten of their people working as AI engineers or technical specialists rather than consultants. Most are nowhere near that.
This is the same shift I described in the rise of the hybrid professional. The difference now is that the labs are competing for the same hybrids.
Integrators lose revenue first, strategy houses lose AI talent first
Integrators such as Accenture and the Big Four will feel lab-backed consultancies first in revenue, because the labs are going after the implementation work they sell. Strategy consulting firms will feel it first in people.
Revenue can be won back with a better proposition. A team of senior AI leaders who have left for equity in a lab-backed venture usually does not come back.
That matters more because partner moves are increasingly team moves. When a senior data and AI leader leaves, the managers who make the outcome happen tend to follow.
A strategy house that loses two or three of those people loses the delivery depth that justified its day rate in the first place.
Independence is the strategy house’s real edge
Strategy consulting firms have one advantage the lab-backed consultancies cannot copy: independence from any single model provider. A consultancy part-owned by Anthropic will struggle to tell a client to use someone else’s model.
As a former Big Four AI leader put it to me, “you can’t really put yourself in that dependency.” Expect every rival pitch against the Anthropic and Hg venture to make the same point.
That edge is only real if the firm has people who can deliver across three vendors. Independence without delivery depth is just a slide.
What winning strategy firms will hire for
The strategy firms that come out ahead will hire senior leaders who have sold work where the fee depended on the result, sat inside a client’s operation, and can work across models without a favourite. They will hire them with their teams, and structure equity to compete with the labs.
What most will still get wrong is the brief. Firms still briefing for a rainmaker with no delivery depth behind them are hiring for 2023.
The question every partnership should ask this year is simple. Are we hiring the people our model needs next, or replacing the partners it needed last?
Read the original article
Further reading from Strat-Bridge
- The “McKinsey of AI” Is Really About Internalising TransformationA PE-backed AI venture marks a structural shift: private equity is starting to internalise AI transformation rather than…
- Why AI Makes Senior Consultants More ValuableAI is reshaping consulting delivery rather than replacing consultants. Why judgment, execution and senior talent are becoming more…
- Consulting Is Being Pushed to Own the Outcome, Not Just Define ItBCG's move into interim management signals a broader shift in consulting: from advising on the answer to being…
- Consulting Team Moves & Lift-Outs — how they workPartner-led team moves, practice builds and talent-led acquisition support for consulting firms across the UK, DACH and Europe.…
Work with Strat-Bridge
Strat-Bridge is a retained executive search firm placing Partner & Director-level leaders into strategy and management consulting firms across Europe.
Hiring senior consulting talent? Book a discovery call. Exploring your next leadership move? Join our leadership network.
Ben Appleton is the founder of Strat-Bridge, a specialist executive search partner to the management consulting industry. He works with global consulting firms and senior leaders across the UK, Germany, Switzerland, and beyond — helping them build capability at the Partner and Director level.
Connect with Ben on LinkedIn or email ben@strat-bridge.com.