Summary: Anthropic and the buyout group Hg are setting up an independent consultancy to embed AI engineers inside European businesses, according to the FT. It is the third lab-backed delivery arm this year, and it moves AI distribution away from consulting firms and towards private equity.
- Anthropic and Hg plan a European AI consultancy with hubs in London and Berlin, aiming to build a company worth more than $10bn within five years, the FT reports.
- The Anthropic and Hg venture follows Ode in the US and the OpenAI Deployment Company, making three lab-backed delivery arms backed by private equity in 2026.
- Private equity is becoming the distribution channel for enterprise AI, with portfolio companies acting as a ready-made client base.
- Anthropic now partners with Accenture and Deloitte while backing a firm the FT says threatens their AI implementation businesses.
Anthropic has stopped waiting for a European transformation partner. It is building one.
According to the FT, Anthropic and Hg have agreed to set up an independent Anthropic consultancy that will embed AI consultants and engineers inside European businesses. Hubs in London and Berlin. Launch expected by the end of this year.
In February, OpenAI signed Frontier Alliances with McKinsey, BCG, Accenture and Capgemini. I wrote then that OpenAI had chosen its consulting corner, and asked who would become Anthropic’s preferred transformation partner.
The answer is Anthropic.
This is not a one-off. Anthropic launched Ode in the US with Blackstone and Hellman & Friedman. OpenAI launched its own deployment company in May. Each one pairs a frontier lab with buyout capital.
The labs are no longer renting distribution from consulting firms. They are building their own, and private equity is supplying the clients.
What the Anthropic Consultancy Is
The Anthropic consultancy is a planned independent company, backed by Anthropic and the London buyout group Hg, that will place AI consultants and engineers inside European companies, according to the FT.
The engineers will lead the design of new AI products or support work a client already has under way. The firm will also work with Hg’s own portfolio companies.
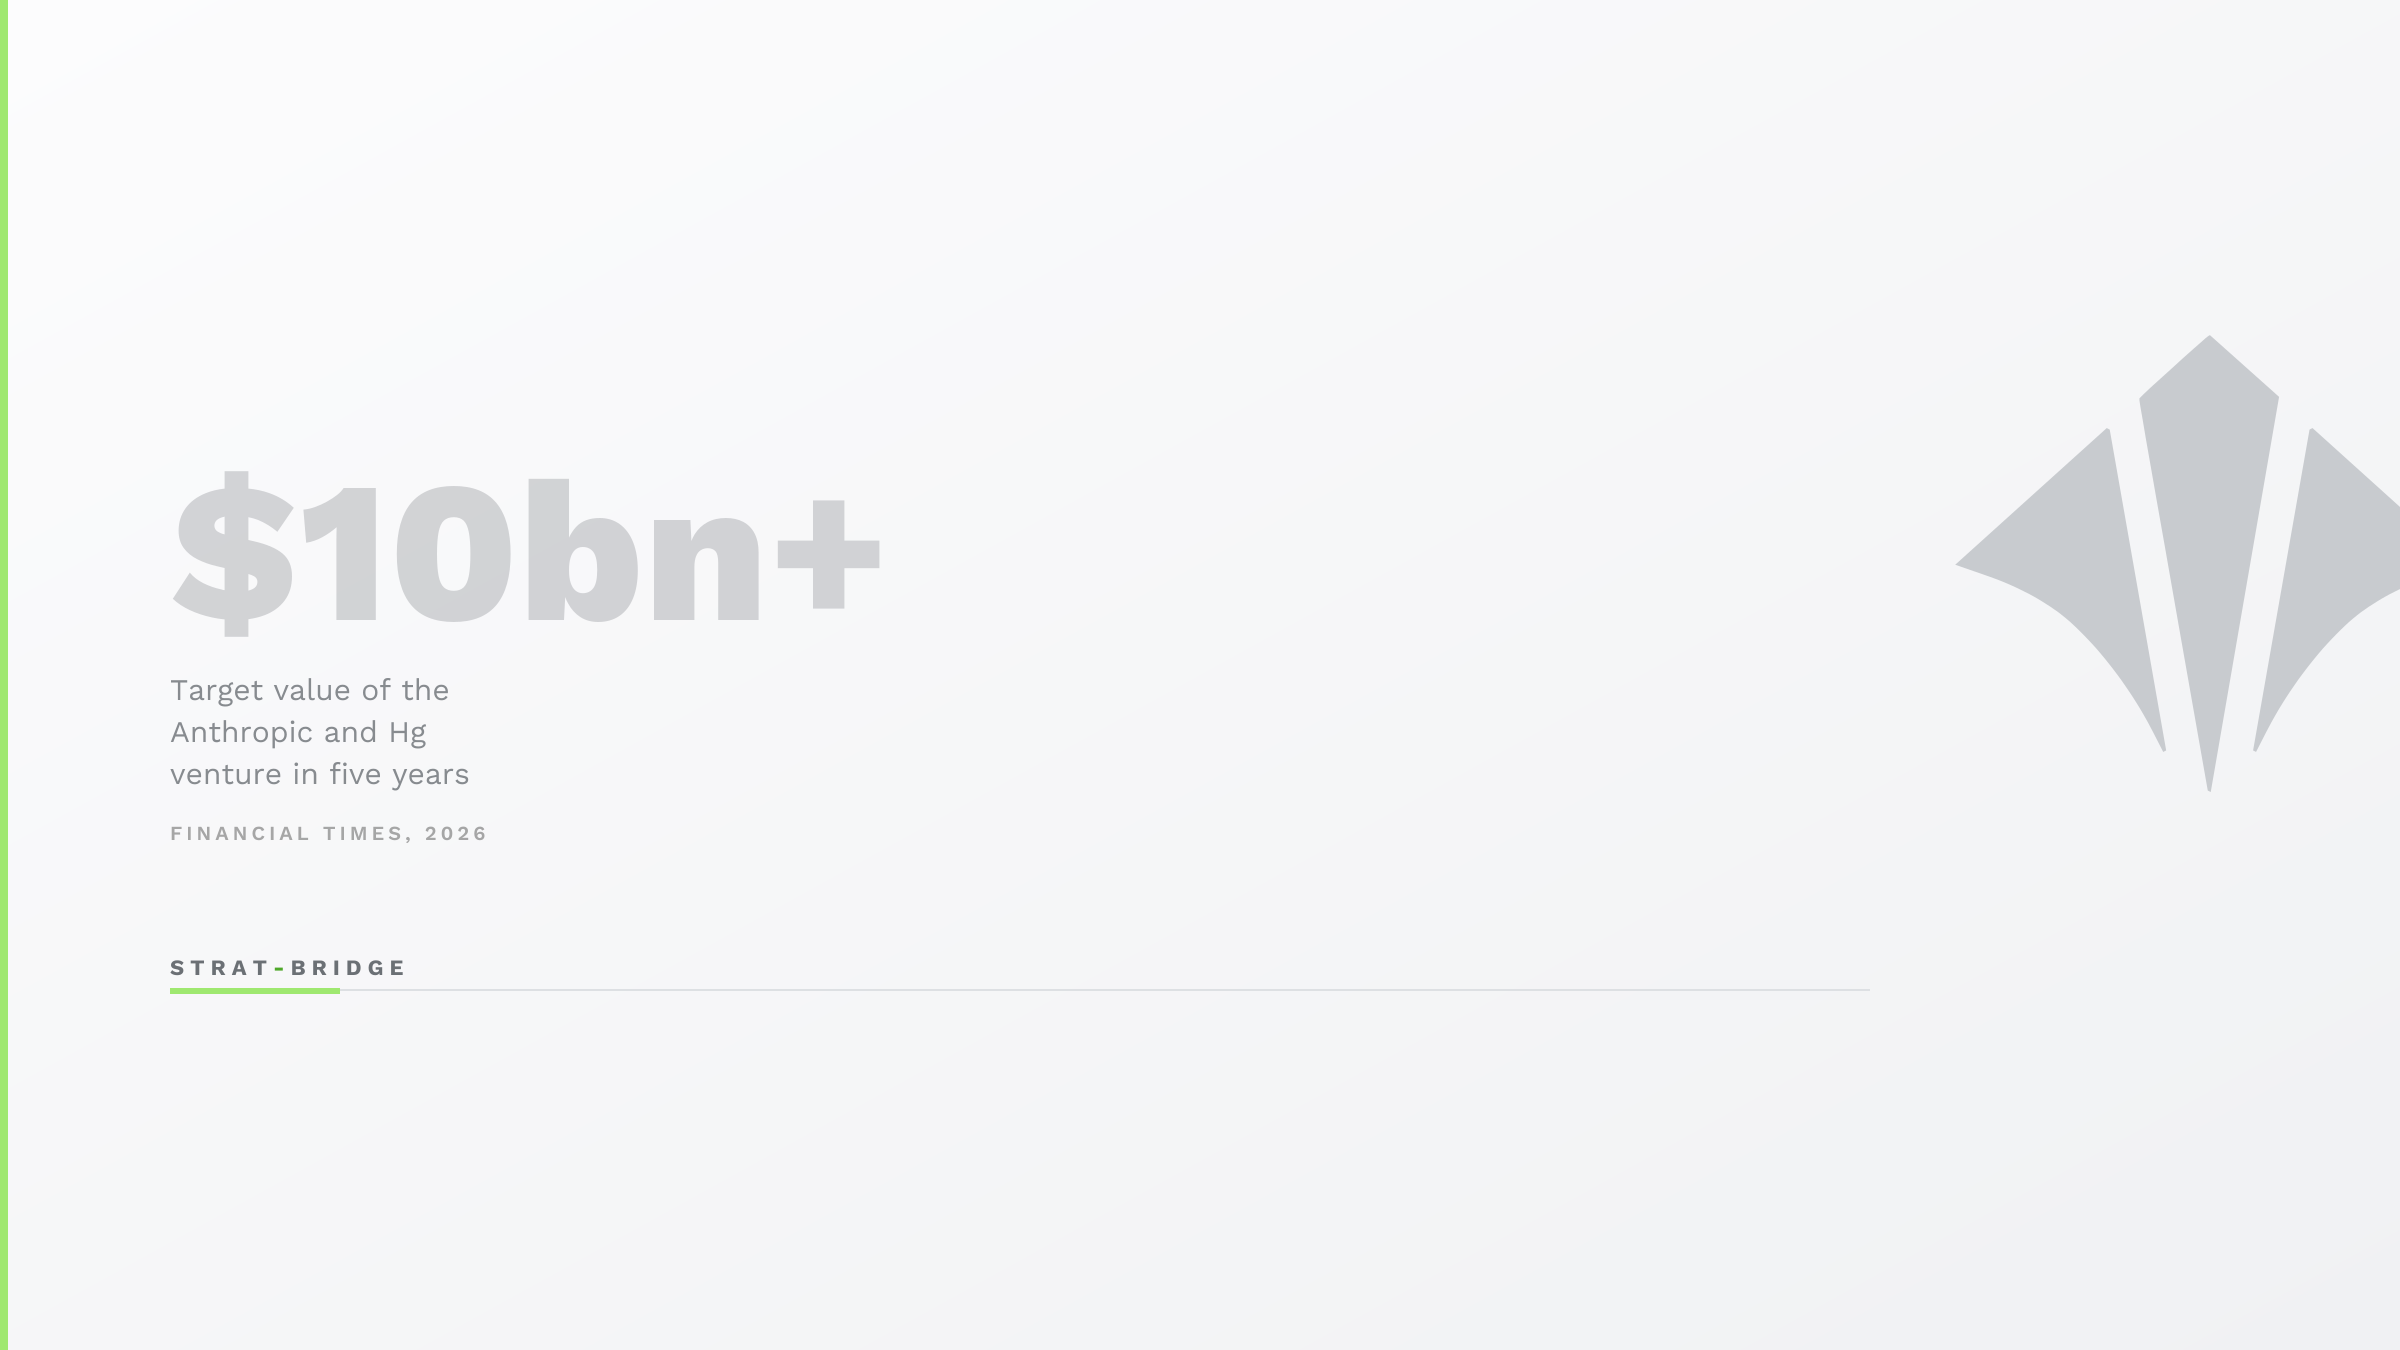
Anthropic will invest from its balance sheet. Hg will invest from funds it manages, including the London-listed HgCapital Trust. The FT reports that the two aim to build a company worth more than $10bn within five years.
The focus is software companies selling to business clients, and other white-collar groups. That is Hg’s home ground.
One caveat. The FT’s report relies on people familiar with the matter. Hg and Anthropic declined to comment, so the detail may still move.
Three Labs, Three Private Equity Partners
Frontier AI labs now run three dedicated delivery arms with private equity backing, and all three have appeared in 2026.
Ode, launched with Blackstone and Hellman & Friedman, carries $1.5bn in planned investment in the US, with Goldman Sachs and Apollo among its other investors, according to the FT. The OpenAI Deployment Company followed in May with TPG, Advent, Bain Capital and Brookfield. Anthropic and Hg now bring the model to Europe.
In September I described Ode as a fifth consulting model being assembled: frontier models, investment capital, client access and embedded delivery, put together rather than grown.
The European version confirms the pattern. It is no longer one experiment. It is how the labs intend to reach the enterprise.
Why the Anthropic Consultancy Runs Through Private Equity
The Anthropic consultancy runs through private equity because Hg owns the clients it needs: a portfolio of more than 60 software and services businesses that must prove they can become AI businesses before exit.
Hg already has a team of 150 AI experts deploying the technology across its portfolio, the FT reports, and the new business will not replace them. Its holdings include Visma, AuditBoard and OneStream, which Hg acquired for $6.4bn this year.
The pressure is real. Advances in AI triggered a sell-off in software stocks earlier this year, the FT notes, and buyout firms have been trying to show their software assets can make the shift.
So the sponsor signs, and the portfolio company implements. The lab gets usage. The fund gets an AI story to take to exit.
This is the logic I flagged in May, when I argued that private equity is internalising transformation. Hg is now doing it at continental scale.
Implementation Firms Carry the Most Exposure
Accenture and the Big Four carry the most exposure to lab-backed consultancies, because embedding engineers to build AI into products is the core of their technology advisory business.
The FT names Accenture, Deloitte, EY, KPMG and PwC as the firms under threat. Their AI practices sell exactly what this venture will sell: engineers inside the client, building and deploying.
Accenture is already rebuilding around that work. As I wrote this month, consulting headcount no longer drives growth. A lab-backed rival with captive portfolio clients makes that harder.
My read: strategy firms are less exposed, for now. Board-level framing and the trust to move a CEO are slow to build inside a joint venture. Engineers can be hired in a year. A partner’s client book cannot.
Engineers can be hired in a year. A partner’s client book cannot.Ben Appleton, Strat-Bridge
Anthropic Is Partner and Competitor at Once
Anthropic is now both a partner to and a competitor of the large firms that distribute Claude.
In December 2025, Accenture launched an Anthropic Business Group and said about 30,000 Accenture professionals would be trained on Claude. Two months earlier, Deloitte agreed to make Claude available to 470,000 people.
Those firms are now watching their model provider back a European consultancy that, in the FT’s framing, threatens their AI implementation work.
That tension is not unusual in technology. Software vendors have long sold through integrators while building their own services arms. It is new for consulting partners who built practices on the assumption that the lab needed them.
Expect the questions inside those practices to sharpen. Who owns the client when the lab’s own venture pitches into the same portfolio company?
Independence Is the Anthropic Consultancy’s Weak Point
The Anthropic consultancy’s weakest point is independence, because a firm part-owned by a model provider will struggle to recommend a rival’s model.
Clients have paid consulting firms for neutrality for decades. A former Big Four AI leader put it to me plainly: “you can’t really put yourself in that dependency.”
In my view, every rival pitching against this firm will lead with that line. In Europe it lands harder. An AI partner I spoke to recently described growing client concern about handing organisational knowledge to a third-party model.
There is a commercial angle too. The FT reported last week that Anthropic’s revenue growth slowed in the third quarter, ahead of a planned IPO. Services revenue pulls usage behind it. Clients will notice.
The Talent Market Gets Tighter
A London and Berlin launch by the end of 2026 means the Anthropic and Hg venture is hiring senior AI delivery leaders now.
The profile is narrow. Engineers who can sit inside a client and ship, plus a thin senior layer who can hold a CEO conversation and carry delivery risk.
That profile sits today at Accenture, the Big Four, the strategy firms’ tech units and AI-native boutiques. Senior data and AI leaders are already the most contested hires I see. One candidate this year put technology-side packages for AI leadership at €600-800k and more.
Lab-backed equity in a business targeting $10bn adds another bidder. Firms that wait for a resignation letter before making the case to stay will lose that argument. This is where senior hiring becomes a strategic lever, not an admin task.
It also raises the stakes on how private equity reshapes the partnership. The buyout funds now compete for consulting talent on two fronts: as owners of firms, and as backers of the labs’ delivery arms.
What the Anthropic Consultancy Means for Consulting Firms
The firms that win will decide where they sit before the market decides for them. Neutral adviser across models, certified integrator for one lab, or a direct competitor to the lab-backed ventures. Each is viable. Drifting between them is not.
What many will still get wrong is treating this as a technology partnership question. It is a distribution and talent question. The labs have found a channel that does not run through consulting firms, and they will staff it from consulting firms’ best AI people.
Read the original article
Further reading from Strat-Bridge
- OpenAI Just Became a Consulting FirmOpenAI just entered the consulting market with a $10M+ enterprise offering, embedding engineers into client operations.
- Why AI Still Needs Management ConsultantsAI is reshaping management consulting rather than replacing it. Why McKinsey, BCG and Deloitte are partnering with AI…
- The Software Consulting ModelConsulting is being rebuilt around code and data. IBM’s “service as software” model signals a major shift as…
- Consulting Team Moves & Lift-Outs — how they workPartner-led team moves, practice builds and talent-led acquisition support for consulting firms across the UK, DACH and Europe.…
Work with Strat-Bridge
Strat-Bridge is a retained executive search firm placing Partner & Director-level leaders into strategy and management consulting firms across Europe.
Hiring senior consulting talent? Book a discovery call. Exploring your next leadership move? Join our leadership network.
Ben Appleton is the founder of Strat-Bridge, a specialist executive search partner to the management consulting industry. He works with global consulting firms and senior leaders across the UK, Germany, Switzerland, and beyond — helping them build capability at the Partner and Director level.
Connect with Ben on LinkedIn or email ben@strat-bridge.com.